
Part 1
I’m going to explain the homerun opportunity in what Trump Accounts can become. And while you read this, please throw out all your preconceived notions about how much money you think an 18-year-old should have. Get rid of the concept of the haves and the have nots. Dismiss the idea that generational wealth is only for the wealthiest. Reverse negative predictions that our kids of today will have less money than their parents.
“Instead - embrace the possibility that we are at the forefront of the greatest generational wealth creation at a scale we’ve never seen. And the design of this program is to create wealth across the entire socioeconomic spectrum.”
When I was a young man in college my assumption was that wealth was suddenly realized. A huge financial transaction win and presto – someone becomes rich. Thankfully, that was a misguided assumption. Wealth is not created immediately. It takes contribution, growth, and most importantly, it takes time.
I’m going to use sycamore trees I planted in my yard as an example. Sycamore is a smooth white bark tree, stately, massively tall with long sweeping limbs reaching for the sun. The sycamore trees we enjoy today sprouted from the ground 100 years ago.
I planted two rows of sycamore trees along a pathway by the canal in our yard. I’m 54 years old. I’ll never see them in full splendor. And so, I didn’t really plant them for me. I spaced them appropriately to maximize what they can become 50 to 100 years from now. Other people, maybe within my family, maybe complete strangers, decades from now will someday enjoy the gift these trees became.
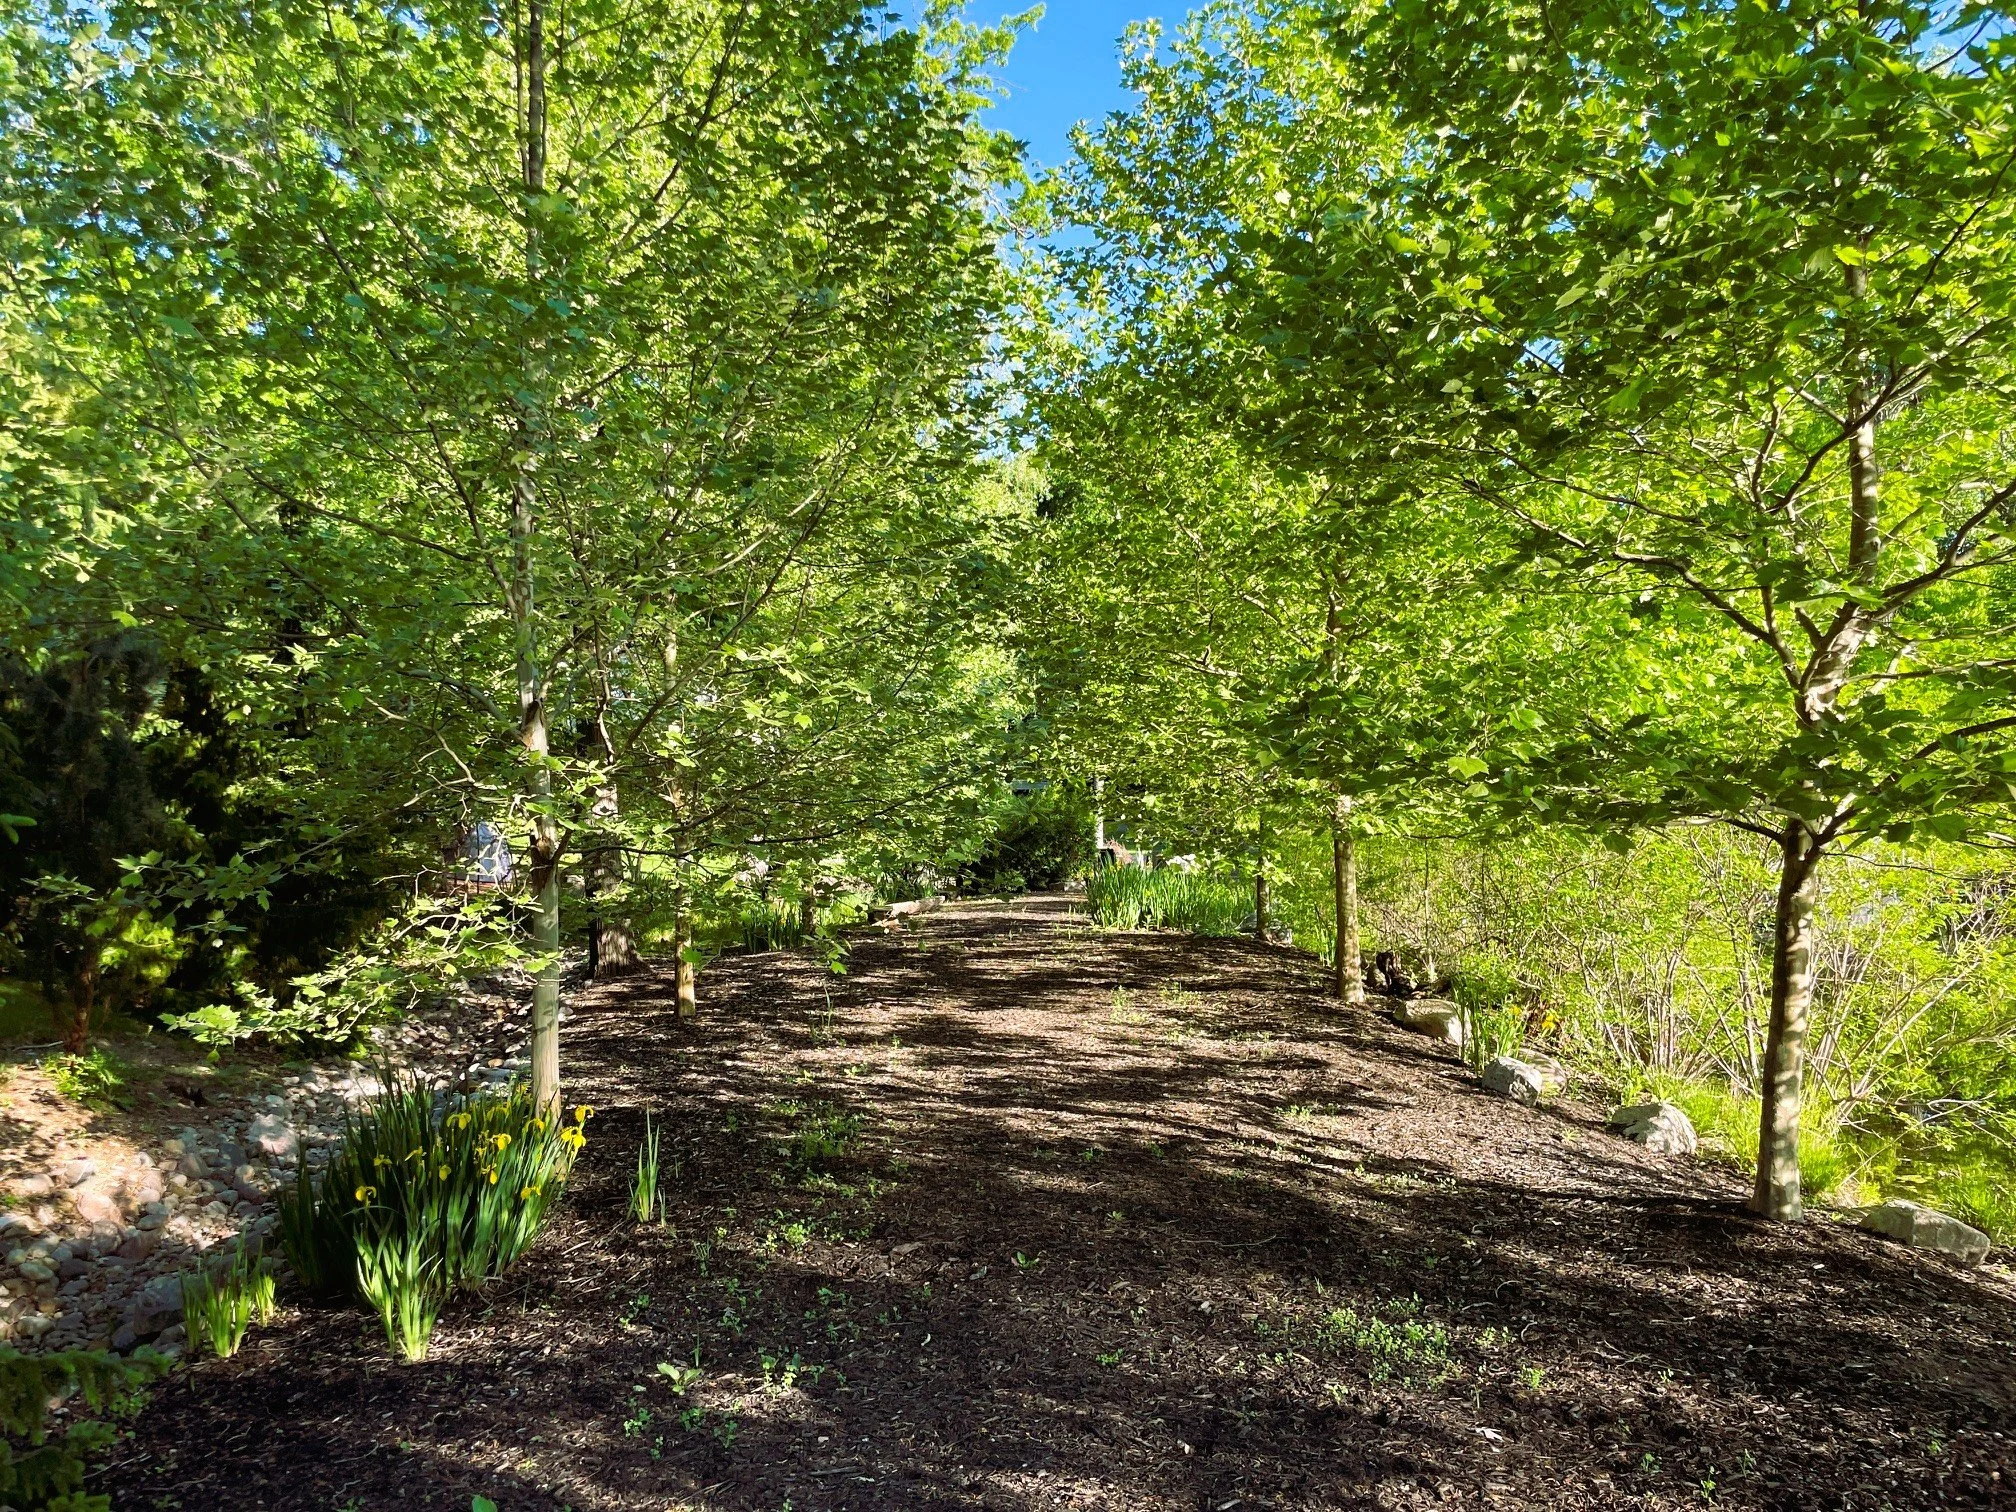
I could have planted willows or other fast-growing trees that reached maturity in a decade. But I felt this row needed sycamores. And I wanted it to become what it could be. In nature, we benefit today from what others planted or allowed to stay rooted. Not for their own benefit but for the benefit of nature and those that come after.
“Now wipe the slate clean with the idea that there are rich kids and poor kids. And like my trees, imagine a future of what things could become.”
For the first time in American history, we have the opportunity to raise an entire generation of children who participate in the wealth created by our economy. When the stock market rises, wealth grows for those who own it. Imagine a generation where nearly every child is an owner, where economic growth builds wealth not just for those who already have money, but for those who historically had none.
And sure, it’s easier for a wealthy family to fully fund a Trump account for their child than for a family with less money. But what’s hugely important to understand is that there is a uniform platform for everyone to participate equally. And I mean everyone. Every U.S. citizen child born from 2025 through 2028 with a Social Security number valid for employment is eligible for a $1,000 government deposit in a Trump Account. All a parent or legal guardian must do is claim it on behalf of that child. The child owns the account, and it will turn into an IRA for that child at age 18.
Why this works far beyond the basic math
The homerun math itself is fantastic. Funding a Trump account at $5,000 per year for 18 years, a $90,000 total contribution, can turn into about $30 million of tax-free retirement distributions over 30 years. Yep, that’s right - $30 million of income. Assumes a 10% return during growth and 6% return during retirement income distribution.
“But this is even bigger than that. When you don’t have money it’s difficult to imagine a day when you could have millions. And when you have millions, it’s difficult to understand how people could think they could never have money.”
The trick is to get people to realize what’s possible, so that they take the appropriate steps to get there. I wrote a book and have a podcast called “Wealth Is a Choice”. I believe, in however we want to measure “wealth”, that it’s our choices more often than circumstances, that determine our futures.
To build financial wealth, a person needs to participate. And now, with a Trump Account, a baby can participate from day 1. There is an open architecture platform that allows funding into the Trump Account from multiple sources. The opportunity for this child to experience wealth goes way beyond the parents’ financial limitation to invest.
The child learning, at such a young age, the value of participating in the United States stock market is just one piece of the equation. The account is overseen by a “responsible party”, namely the parent or guardian, many of whom are also learning for the first time the ease and power of participating in the market. Access and knowledge to investing in the market are tremendous obstacles in reducing the wealth divide. This program greatly reduces those obstacles.
“Access and knowledge to investing in the market are tremendous obstacles in reducing the wealth divide. This program greatly reduces those obstacles.”
The infrastructure for funding is massive. Within the circle of community for that child – parents, grandparents, other relatives and friends, anyone can contribute into the Trump Account.
But it goes way past that. Companies, philanthropists and charities can contribute too, and the program is built so that large-scale gifts reach massive numbers of children equally. And this is happening already. The Michael and Susan Dell Foundation pledged $6.25 billion to deposit $250 into Trump Accounts of up to 25 million children. The child must be born between 2016 and 2024 and live in a zip code with median household income of $150,000 or less.
This is the most direct transfer of wealth ownership to American children we’ve ever had.
The Trump Accounts in one paragraph
Trump Accounts let anyone, most often parents and grandparents, put up to $5,000 a year into an investment account in a child's name. The money is invested in low-cost U.S. stock index funds and grows untaxed until adulthood. Once the child becomes an adult, the account becomes a traditional IRA, and it can be converted to a Roth IRA.
“Pay the tax while the young adult is in a low bracket, and every dollar of growth can come out tax free in retirement ”
The home-run game plan
1. Open it at birth. Claim the $1,000 federal deposit if the child was born 2025–2028.
2. Fund the full $5,000 every January through the year the child turns 17. That's 18 deposits, $90,000 in total.
3. Let it grow untouched. No access, no temptation, no withdrawals possible.
4. Convert to a Roth in the right year. After 18, ideally when the young adult isn't subject to the kiddie tax and has little other income. Spread it over a few years if needed and pay the tax from outside the account.
5. Leave the Roth alone until retirement. That's when the long compounding does its work.
6. The bonus kicker - add a custodial Roth IRA as soon as the child has a job, funded up to their earnings, to build a second tax-free account alongside.
What $5,000 invested annually can grow into
Swipe sideways to view the full table.
| If the account earns | At 18 | By about age 60 | Paid out over 30 years at 6% |
|---|---|---|---|
| 6% a year | about $164,000 | about $1.9 million | about $4.1 million ($138,000 a year) |
| 8% a year | about $202,000 | about $5.1 million | about $11.2 million ($372,000 a year) |
| 10% a year | about $251,000 | about $13.7 million | about $29.9 million ($998,000 a year) |
Assumes $5,000 at the start of each year for 18 years. The payout column assumes level annual withdrawals at the end of each year for 30 years, with the remaining balance earning 6%. Future dollars; returns are not guaranteed. Whether the income is taxable or not depends on if the account was converted to a Roth (tax free) or left as a regular IRA (taxable).
Creating generational wealth
• It starts compounding decades earlier. Most people begin retirement saving in their 20s or 30s. This gives a child a 25-year head start, and time is the most powerful variable in the math.
• It moves money out of parents’ or grandparents' estate at no gift tax cost, usually with no paperwork at all.
• It ends in the best kind of account. A Roth IRA has no required withdrawals for its owner and passes to the next generation's heirs income-tax-free.
• It teaches as it grows. A child who watches an account grow from birth learns, in a concrete way, what investing and patience can do.
• It's affordable to start small. Even a few hundred dollars a year, plus the $1,000 seed, compounds into meaningful money over 60 years.
A paradigm shift: raising a child who reaches 18 with equity
I’m going to challenge our expectation about how much wealth we should and are able to help our children accumulate before they turn 18.
American families spend enormous sums raising children, yet most children reach 18 owning almost nothing. The money is already flowing; the question is whether any of it is directed toward ownership.
What it costs to raise a child
Raising a child to 18 now costs more than $300,000, according to a 2026 LendingTree analysis, a figure consistent with inflation-adjusted estimates based on the USDA’s last official study. And that covers only the basics: no activities, vacations, or college. After all that money is spent the child reaches age 18 with no equity.
“Why should that be normal? Redirect some of that expense into equity and change the trajectory.”
Put next to that number: fully funding a Trump Account costs about $90,000 over 18 years, $5,000 a year. And it can be shared among parents, grandparents and others. Even a fraction of it changes a child's starting line
We have a chance to reprioritize childhood expenses
Youth sports are a good experience for many children, and some, like travel sports, are expensive. The Aspen Institute's Project Play survey found families spent an average of $1,016 on a child's primary sport in 2024, up 46% since 2019, and about $1,500 across all sports. Club and travel teams cost far more: one study of AAU and club families found over $2,000 a year in club fees plus over $2,000 in travel, so $5,000 a year or more is common.
What if some of that money went to ownership instead?
Swipe sideways to view the full table.
| Redirected each year, ages 8–17 | Total redirected | Value at 18 (8% a year) | Value at about 60 (8% a year) |
|---|---|---|---|
| $5,000 (a typical travel-team year) | $50,000 | about $78,000 | about $2.0 million |
| $2,500 (half) | $25,000 | about $39,000 | about $1.0 million |
At 6%, the $5,000 row reaches about $808,000 by 60; at 10%, about $4.8 million. Assumes deposits at the start of each year and a Roth conversion at 18 with tax paid separately.
The point isn't that families should give up sports. It's that every recurring expense has an opportunity cost, and most families never see it laid out.
“A family that keeps a child in sports but trims one tournament trip or asks grandparents to fund the Trump Account instead of buying gear, is making a different kind of choice: one where childhood spending also builds a future of equity.”
The mindset shift: most Americans work to pay their bills. Flip that mentality. Work to create wealth with earned income and then also pay some bills. Raising a child can follow the same principle: a child who reaches 18 with a meaningful account, and the habits that come with watching it grow, enters adulthood owning a piece of the economy rather than starting from zero or even negative.
Sources: LendingTree cost of raising a child study; Nancy Folbre on Brookings and USDA estimates; Aspen Institute Project Play family spending survey; RAIS study on AAU and club sports costs.
Leveling the playing field
The amount of wealth we create is determined by three things. 1) How much wealth we buy. 2) How much return our wealth grows by. And 3) How much time we have for wealth to grow.
That last one – time – that’s the most powerful of all. But let’s look at all three and reflect on the wealth disparity in our country. Of those three components, no matter a family’s current wealth position, all American children born today have the same opportunity in 2 of the 3 components: time and investment returns. Every child can begin investing in the year they’re born, and under today’s program, their money is invested in the same S&P 500 index strategy.
“Whether a child comes from a wealthy family or one with very little money, the opportunity to participate in the growth of the American economy is the same.”
They just need a parent or guardian to open the account for them. So, during childhood, every newborn in America has the same opportunity to benefit from time and investment returns.
The remaining variable is how much money gets contributed. And here’s where the platform shines. Contributions aren’t limited to what parents can afford. Grandparents, relatives, employers, and philanthropists can all participate in building that child’s financial future.
Besides Dell, others are announcing their proposals to contribute. From the time I wrote this article to posting it – Elon Musk has now announced his goal of gifting Space X stock to every child in America.
There is one thing that bums me out about the Trump Accounts. They didn’t exist until my kids were in their 20s. I cannot fathom how different their lives would be right now if this had existed when they were babies.
Get started and then find a way.
Life is complicated and this also has nuances to discover. Let’s examine that next in Part 2.
None of this is guaranteed: markets fluctuate, the child controls the money at 18, and the conversion must be timed well.
The Fine Print: Key Numbers, Rules, Pitfalls, and Limits
Part 2
The Trump Account to Roth homerun works only if a handful of rules are respected. This is the condensed guide covering many of the finer print details.
Key Numbers (2026)
Swipe sideways to view the full table.
| Item | Amount |
|---|---|
| Annual Trump Account limit, all family and employer sources | $5,000 per child (indexed after 2027) |
| Employer contribution, tax-free to employee | Up to $2,500 per employee, counts toward the $5,000 |
| Federal seed deposit | $1,000, children born 2025–2028, U.S. citizens |
| Annual gift tax exclusion (includes the Trump contribution) | $19,000 per giver, per child |
| Lifetime gift and estate exemption | $15 million per person |
| Kiddie tax threshold on unearned income | $2,700 |
| Regular IRA limit after 18 (requires earned income) | $7,500 |
| Fund expense cap during childhood | 0.10% a year |
What is the kiddie tax?
The kiddie tax is a rule that stops families from shifting unearned income to children to have it taxed at a child's low rate. Above a small amount ($2,700 in 2026), a young person's unearned income is taxed at the parents' tax rate instead of their own.
It applies to children under 18, to 18-year-olds, and to full-time students ages 19 to 23. For 18-year-olds and students, it applies only if their own earnings don't cover more than half of their support.
“A Roth conversion counts as unearned income. If the kiddie tax applies, the converted amount is stacked on top of the parents’ income and taxed at their bracket, which for many families means 32–37% instead of 10–12%. Converting when the young adult is outside the kiddie tax can cut the tax bill by more than half.”
How to open a Trump Account
Swipe sideways to view the full table.
| Step | What to do |
|---|---|
| 1. Check eligibility | The child needs a Social Security number valid for employment and must not turn 18 by December 31 of this year. |
| 2. Make the election | Go to TrumpAccounts.gov and elect online, or file IRS Form 4547 (on its own or with your tax return). For a child born 2025–2028, check the box to claim the $1,000 government deposit. |
| 3. Watch for activation instructions | Treasury confirms the election and sends instructions. The account is created at Robinhood, Treasury's initial trustee; you don't choose a firm. |
| 4. Activate in the official app | Download the Trump Accounts app (Apple App Store or Google Play) or use the website. Verify your identity and accept the account agreement. The adult who activates becomes the responsible party. |
| 5. Fund it | Link a bank account and contribute by bank transfer or debit card; recurring deposits are available. Contributions count in the year Robinhood receives them, so deposit by mid-December. |
| 6. Choose investments (optional) | Every account starts in the default S&P 500 ETF; switching among approved funds is being rolled out. |
Avoid look-alike sites. Several private websites use names similar to the official program. Start at TrumpAccounts.gov and follow its links to the app. The app is branded "Trump Accounts," not Robinhood.
Before relatives contribute, check the app for the current way for grandparents and others to deposit directly, and agree on who will use the $5,000 each year.
The rules that shape the plan
Swipe sideways to view the full table.
| Rule | What it means for the plan |
|---|---|
| One account per child, owned by the child | Gifts are irrevocable and can't move to a sibling |
| Deposits end December 31 of the year the child turns 17 | About 18 years of contributions for a newborn |
| No access before 18 | Only exceptions: a rollover to an ABLE account at 17, or death |
| Treasury chose Robinhood as the initial custodian for all Trump Accounts | The law allows families to transfer accounts to other qualified firms, and Treasury has said that option is coming |
| Children in foster care are eligible | A state child welfare agency can open and manage the account for a child in its custody, or a foster parent may if the child is their dependent. When the child leaves foster care, the role passes to the new guardian. |
| No further contributions the year the child turns 18. At their 18th birthday, Robinhood as current custodian moves it to a regular traditional IRA | When the child turns 18 the account structure changes to ordinary IRA rules. |
| Roth conversions are pro rata, never basis first | Each Roth conversion is part tax-free, part taxable, figured at year-end across all of the young adult's traditional, SEP and SIMPLE IRAs |
| Basis must be proven by the family after 18 | Keep a contribution log; it goes on the young adult's Form 8606 |
| Only after-tax family contributions are basis | The $1,000 seed, charity and employer money, and all growth are taxable |
Pitfalls
Swipe sideways to view the full table.
| Pitfall | Why it hurts | How to avoid it |
|---|---|---|
| Converting to a Roth while the kiddie tax applies | Taxed at the parents' rates, stacked on their income; can more than double the bill | Convert to Roth in years the young adult is outside the kiddie tax |
| Siblings converting to Roth in the same year | Their incomes stack together on top of the parents' income, pushing each other into higher brackets | Stagger siblings' Roth conversions into different years |
| Paying the Roth conversion tax from the account | Counts as a withdrawal, usually with a 10% penalty | Pay the tax from outside the account if possible. |
| Rolling a 401(k) into an IRA before conversions finish | Dilutes the tax-free share of every conversion | Leave employer-plan money in the plan until conversions are done |
| Losing track of basis | Without records, the IRS can treat the whole account as taxable | Keep a contribution log from day one |
| Going over the $19,000 gift exclusion, superfunding a 529, or gift splitting | Requires a Form 709 and removes the Trump gift from the IRS safe harbor | Keep each giver's total per child within $19,000; give from own or joint accounts |
| Uncoordinated family giving | The first $5,000 deposited fills the year. Excess deposits could be rejected or directed into an UGMA/UTMA. | Agree and coordinate who gives what each year |
| Counting on it for college or emergencies | No access before age 18; early withdrawals after 18 prior to retirement cost tax and penalties | Use a 529 or other savings for nearer-term needs |
| A child with a disability | The balance may affect SSI and Medicaid after 18 | Consider the ABLE rollover at age 17; consult a special needs attorney |
| Spending at 18 | No legal protection exists against a young adult cashing out | Start financial education early |
What a Roth Conversion looks like on hypothetical $200,000 account at age 18
Swipe sideways to view the full table.
| Determine Basis | Determine Gain | Tax Owed | How to pay the tax |
|---|---|---|---|
| $5,000 contributed for 18 years = $90,000. This is total after tax family contributions. | $200,000 - $90,000 basis = $110,000. This is taxable income in a Roth conversion. | $110,000 x 22% = $24,200. Assuming a 22% effective federal rate on the taxable conversion + applicable state taxes. | Ideally from an outside account, for example, using funds that had been saved into an UTMA. |
A Roth conversion is not mandatory and may not be advisable. It is an exceptionally powerful strategy if the intended purpose of the funds is to leave for retirement. The tax rates need to be calculated accurately prior to considering a Roth conversion.
Money competes: the four core child accounts
There are more places to save money than most people have available to save. I use the phrase “Money Competes” to describe this phenomenon.
Money always lands somewhere but not always where we wish it could.
“In a perfect world, families would use all four: a Trump Account for retirement, a 529 for education, a UTMA for flexibility, and, once the child has a job, a custodial Roth IRA. Each does a job the others can’t.”
Swipe sideways to view the full table.
| Trump Account | 529 plan | UTMA/UGMA | Custodial Roth | |
|---|---|---|---|---|
| Best for | Lifetime retirement wealth | College, K-12 tuition, trade school | Any expense that benefits the child | Lifetime retirement wealth |
| 2026 limit | $5,000 per child, all sources | No annual cap; $19,000 per giver without a gift tax return, or $95,000 front-loaded – Super Funding a 529 Plan | No cap; over $19,000 per giver needs a gift tax return | $7,500 or earned income of the child, whichever is less. |
| Who controls | Responsible party until 18, then the child | The owner, indefinitely, usually a parent or grandparent | Custodian until 18–21, then the child | Custodian until 18–21 (by state), then the child |
| Tax on growth | Deferred; tax-free if converted to a Roth | Tax-free for qualified education | Taxed yearly; kiddie tax applies | Tax-free |
| Access | None before 18; penalty-free after 59½ | Anytime; penalty on earnings if not for education | Anytime, for the child's benefit | Contributions anytime, tax- and penalty-free; earnings tax-free after 59½ (and 5 years) |
| If plans change | Belongs to the child permanently | Change beneficiary or roll up to $35,000 to the child's Roth IRA. Subject to eligibility and rollover restrictions. | Belongs to the child at majority | Belongs to the child permanently |
Milestones by age
Swipe sideways to view the full table.
| Age | Action |
|---|---|
| Birth | Get SSN; file Form 4547 with the $1,000 election; set up yearly January deposits; start a contribution log |
| Every year | Confirm who uses the $5,000; check the gift exclusion; save the annual statement |
| First job | Open a custodial Roth IRA funded up to the child's earnings |
| 16–17 | Plan conversion years with the CPA; consider the ABLE rollover if relevant |
| 18th birthday | Account moves to a regular IRA; responsible party's role ends; name beneficiaries |
| 18–24+ | Convert in low-tax, non-kiddie-tax years; keep other pre-tax money out of IRAs |
| 59½ and later | Tax-free Roth withdrawals; no required withdrawals for the owner |
As of October 15, 2026. Proposed regulations and Robinhood's agreement can change.
What to consider now – before the end of the year
Swipe sideways to view the full table.
| If you have a child born since January 1, 2025 | Open a Trump Account | Claim the $1,000 government deposit. You can also deposit up to $5,000. |
|---|---|---|
| If you have a child born between 2016 and 2024 | Open a Trump Account | Claim the $250 Dell contribution if eligible. You can also deposit up to $5,000. |
| If you have a minor child not turning 18 in 2026 | Consider opening a Trump Account | You have until December 31 to make a 2026 deposit of up to $5,000. Deposit by mid-December so the transfer arrives in time. For children turning 17 in 2026 – this is your only year to contribute. |
Trump accounts are a brand new concept and there’s much to unpack here. Especially when considering “money competes” and which strategy is best for a given desired outcome. We are here to help. Please call us at 248-643-6550 or visit our website to email or set up a time to meet.
Thanks,
James -